
Saving money sounds simple until the bills arrive, everyday expenses pile up, and there’s somehow nothing left at the end of the month. That’s why learning how could you make sure that you are paying yourself first regularly and building up your savings? is so important.
The basic idea is straightforward: instead of saving whatever happens to be left after spending, you set aside money for savings before you spend on nonessential expenses. With automation, realistic goals, and a budget that fits your income, this approach can turn saving from something you occasionally remember to do into a regular financial habit.
What Does “Pay Yourself First” Mean?
“Pay yourself first” means treating savings as one of your financial priorities rather than an afterthought.
When your paycheck arrives, you move a predetermined amount into savings before using the remaining money for discretionary spending. In other words, you make saving part of your financial routine.
For example, if you receive $3,000 after taxes and decide to save 10%, you would move $300 into savings first. The remaining $2,700 becomes the amount available for bills, groceries, transportation, entertainment, and other expenses.
The goal isn’t necessarily to save a large amount immediately. Consistency matters more than starting with a perfect number.
How Could You Make Sure You Are Paying Yourself First Regularly?
The easiest way is to remove as much decision-making as possible.
Instead of waiting until the end of the month and hoping you have money left, establish a system that automatically moves money into savings when you get paid.
Here are some practical steps:
- Choose a savings amount.
- Set up an automatic transfer.
- Schedule it around payday.
- Keep savings separate from everyday spending.
- Increase the amount gradually when your income rises.
Once the process is automated, saving becomes much easier because you don’t have to remember to do it every month.
Automate Your Savings
Automation is one of the most effective ways to make paying yourself first a habit.
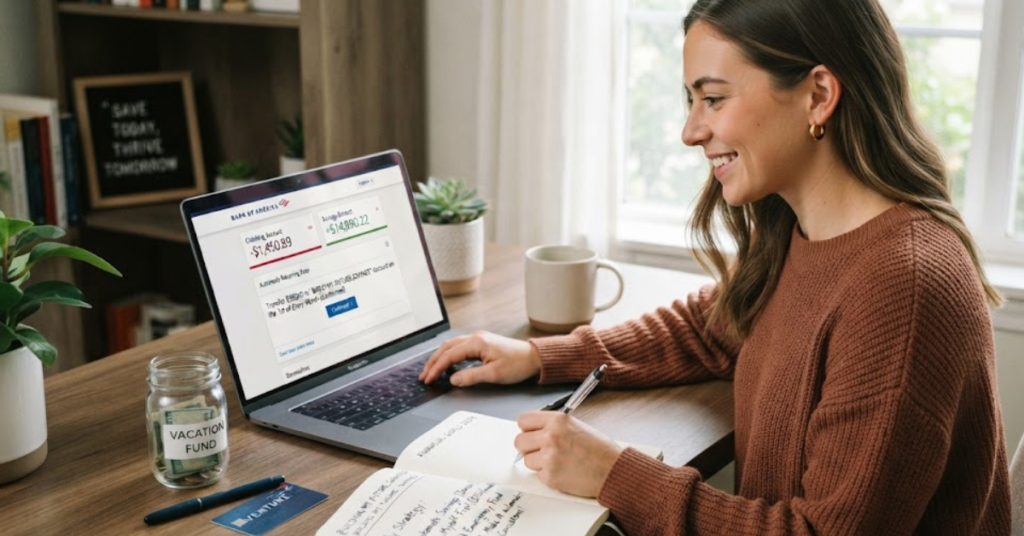
Many banks allow you to schedule recurring transfers from your checking account to a savings account. You can arrange the transfer for the same day or shortly after your paycheck arrives.
For example:
Paycheck → Automatic savings transfer → Bills and everyday spending
This reverses the common habit of spending first and saving whatever remains.
If your employer offers an automatic retirement contribution through a workplace plan, that can also help you save before the money reaches your everyday spending account.
Why Automation Works
Automatic savings can help because it reduces the temptation to spend money that you’ve already decided to save.
You don’t have to ask yourself every payday:
“Should I save this month?”
The system has already made saving part of your routine.
Decide How Much to Save
There’s no single savings percentage that works for everyone. Your ideal amount depends on your income, fixed expenses, debt, financial goals, and current savings.
Some people use a percentage of each paycheck, while others choose a fixed dollar amount.
For example:
- $25 per paycheck
- $50 per week
- 5% of take-home pay
- 10% of take-home pay
- A larger amount when income allows
If money is tight, starting small is perfectly reasonable.
Saving $25 consistently is more useful than planning to save $500 and repeatedly failing to do it.
Build Your Savings Around Specific Goals
Saving becomes easier when you know what the money is for.
Instead of having one vague goal called “save more,” divide your savings into clear objectives.
Common savings goals include:
- Emergency fund
- Car repairs
- Home expenses
- Vacation
- Education
- Major purchases
- Medical or unexpected expenses
- Retirement
Specific goals make it easier to measure progress and stay motivated.
Start With an Emergency Fund
An emergency fund is designed for unexpected expenses rather than planned purchases.
For example, an emergency fund could help cover an unexpected repair, temporary loss of income, or another necessary expense.
A common approach is to begin with a manageable starter emergency fund and gradually work toward several months of essential expenses, depending on your circumstances and How could you make sure that you are paying yourself first regularly and building up your savings?
The important thing is to build it progressively rather than waiting until you can afford a large balance.
Keep Savings Separate From Spending Money
It can be surprisingly easy to spend savings when they’re sitting in the same account you use for everyday purchases.
Consider keeping savings in a separate account so the money isn’t constantly visible alongside your spending balance.
You can organize your money into categories such as:
- Everyday spending
- Emergency savings
- Short-term goals
- Long-term savings
The exact setup isn’t as important as creating a system that makes your savings harder to accidentally spend.
Create a Budget That Supports Your Savings
Paying yourself first works best when your budget accounts for savings from the beginning.
Rather than creating a budget based on what you normally spend and then trying to squeeze savings into the leftover amount, treat savings as a planned expense.
A simple structure might look like this:
| Category | Example |
| Income | $3,000 |
| Savings | $300 |
| Housing | $1,000 |
| Utilities | $250 |
| Food | $400 |
| Transportation | $300 |
| Other expenses | $750 |
These numbers are only an illustration. Your actual budget should reflect your income and necessary expenses.
What If You Can’t Save Much?
Don’t assume that paying yourself first only works for people with high incomes.
If your budget is already stretched, start with an amount that won’t cause you to fall behind on essential bills.
Even a small recurring transfer can establish the habit.
You can also look for opportunities to redirect money, such as:
- Canceling unused subscriptions
- Reducing unnecessary fees
- Cooking at home more often
- Reviewing recurring bills
- Putting part of a raise toward savings
- Saving a portion of occasional extra income
The objective is to create sustainable savings, not to make your budget so restrictive that you abandon it.
Increase Your Savings Over Time
Once automatic saving becomes comfortable, gradually increase the amount.
For example, you might start by saving 5% of your take-home income. After several months, you could increase it to 6% or 7%.
Another simple strategy is to save part of every pay raise.
If your income increases by $200 per month, you don’t necessarily have to increase your lifestyle by the entire $200. You could direct some of that increase toward your savings goals.
This can help your savings grow without making the change feel as painful as cutting existing expenses.
Don’t Forget About Debt
Paying yourself first doesn’t mean ignoring high-priority financial obligations.
If you have high-interest debt, it’s worth considering how savings and debt repayment should work together. Maintaining some emergency savings can help prevent unexpected expenses from immediately going onto a credit card, while additional cash flow may be directed toward expensive debt.
The right balance depends on your circumstances.
A financial plan should account for savings, debt repayment, essential expenses, and long-term goals rather than focusing on only one category.
Make Saving Automatic on Payday
A simple payday routine can make the process almost effortless.
Try this five-step system:
- Receive your paycheck.
- Automatically transfer your chosen savings amount.
- Pay essential bills.
- Set aside money for regular expenses.
- Spend what’s left without dipping into your savings.
The key is that savings happen near the beginning of the process rather than at the end.
Review Your Progress Regularly
Automation doesn’t mean you should completely forget about your finances.
Review your savings system periodically to make sure it still matches your circumstances.
Check:
- Is the savings amount still realistic?
- Have your expenses changed?
- Has your income increased?
- Are you making progress toward your goals?
- Do you need a larger emergency fund?
- Are you accidentally using savings for everyday purchases?
A quick review every few months can help keep your plan on track.
Common Mistakes When Paying Yourself First
Even a good savings strategy can fail if the system isn’t realistic.
Watch out for these mistakes:
Saving Too Much Too Soon
An aggressive savings target may look impressive on paper but become difficult to maintain.
Start with an amount you can consistently afford.
Using Savings for Everyday Spending
If you frequently transfer money back out of savings, your target may be too aggressive or your spending budget may need adjustment.
Ignoring Irregular Expenses
Annual insurance payments, car maintenance, gifts, and other occasional costs can disrupt a budget if you don’t plan for them.
Consider creating separate sinking funds for predictable expenses.
Increasing Lifestyle Spending With Every Raise
As income increases, it’s tempting to spend every additional dollar. Saving part of each increase can help your financial progress keep pace with your earnings.
A Simple Pay-Yourself-First Checklist
Use this checklist to put the strategy into practice:
-
Choose a realistic savings amount.
-
Open or designate a separate savings account.
-
Set up automatic transfers.
-
Schedule transfers around payday.
-
Create an emergency fund goal.
-
Budget for irregular expenses.
-
Review your progress periodically.
-
Increase savings when your income allows.
-
Avoid regularly withdrawing from your savings.
Read also <<< How the Components of Health Are Related to Wellness
Frequently Asked Questions
What is the easiest way to pay yourself first?
The easiest method is usually to automate a transfer from your checking account to savings immediately after receiving your paycheck. This makes saving automatic instead of relying on willpower.
How much should I pay myself first?
There isn’t one correct amount for everyone. Choose an amount that fits your income and essential expenses. Starting with a small, sustainable amount is often better than setting an unrealistic target.
Should I save money before paying bills?
“Pay yourself first” generally means prioritizing a planned savings contribution before discretionary spending. However, essential bills and financial obligations still need to be covered, so your savings amount should be realistic.
Is paying yourself first the same as budgeting?
Not exactly. Budgeting is the broader process of planning how you’ll use your money. Paying yourself first is a specific strategy that places savings near the top of that plan.
How can I make saving money a habit?
Automate your savings, use a separate account, set specific goals, and review your progress regularly. Removing the need to make a new decision every payday can make the habit much easier to maintain.
What if I can’t afford to save 10% of my income?
That’s okay. A fixed amount of $10, $25, or another affordable figure can still help you establish the habit. You can increase the amount later as your financial situation improves.
Should I pay off debt or build savings first?
It often makes sense to maintain some emergency savings while also addressing high-interest debt. The appropriate balance depends on the type of debt, interest rate, income stability, and available cash reserves.
Conclusion
So, how could you make sure that you are paying yourself first regularly and building up your savings? Start by making saving automatic, choosing a realistic amount, and treating that contribution as part of your regular financial plan.
You don’t need a huge paycheck or a complicated strategy to begin. Consistency is the real advantage of paying yourself first. Start with an amount you can maintain, build an emergency fund, adjust your savings as your income changes, and give your money a clear purpose.
The sooner you create a system that saves money before you spend it, the less you’ll have to rely on willpower—and the easier it becomes to build financial security over time.